The Effect on Alternative Investment Like PE and Real Estate by Rising Oil Prices: Private Equity, Real Estate, and Beyond
Oil prices rarely stay quiet for long - and when they move, the ripple effects reach far beyond the gas pump. For accredited passive investors holding positions in private equity, real estate, private debt, and other alternative assets, understanding how energy costs reshape valuations, cash flow, and deal terms is essential to protecting and growing wealth.
Executive Snapshot: Why Oil Prices Matter for Accredited Alternative Investors
Fluctuations in oil prices serve as a macroeconomic driver influencing alternative asset performance across nearly every sector. When Brent crude collapsed from $115 to below $30 between 2014 and 2016, energy-focused funds suffered while consumer-oriented strategies benefited from lower input costs. The reversal came hard: after Russia's invasion of Ukraine in early 2022, oil surged past $120 per barrel, triggering cost-push inflation that forced aggressive central bank tightening. Rising oil prices trigger cost-push inflation and tighter monetary policy, and the downstream consequences hit alternative investments in ways that stocks and bonds often don't prepare you for.
The directional impacts break down roughly like this:
- Higher oil → higher inflation and interest rates → valuation pressure on growth-oriented private equity and venture capital; compressed multiples and higher discount rates
- Mixed effects on income-oriented real estate → rent escalation may lag rising expenses; NNN lease structures fare better than gross leases
- Potential upside for energy-focused funds → midstream infrastructure, energy services, and commodity strategies can benefit directly
- Private debt and floating-rate instruments → yields rise with rates, but credit risk increases for energy-sensitive borrowers
Alternative investments often offer higher returns than traditional investments, but that potential comes with exposure to macro forces like oil that public mutual funds and stock investments rarely force you to confront directly.
For members of the 506 Investor Group - accredited passive investors sharing deal flow and due diligence without sponsor influence - the practical concerns are specific: Will your portfolio cash flow hold up if utilities and construction costs jump? Are the deals you're evaluating underwritten for today's energy environment or for 2020-era assumptions? And are you positioned to capitalize on the opportunities that volatile oil markets create?
This article focuses on practical implications and actionable guidance rather than macro theory, drawing on 2022–2026 data where available.
How Oil Prices Feed Through to Inflation, Rates, and Alternative Assets
The transmission mechanism from oil to your alternative investment portfolio is straightforward, even if the timing isn't always predictable.
Oil functions as a foundational input cost. When crude rises, production costs climb across manufacturing, logistics, agriculture, and construction. Those increases flow into the Producer Price Index (PPI) and eventually consumer prices (CPI). Sustained energy-driven inflation can raise interest rates as central banks respond - exactly what happened during the Fed's aggressive hiking cycle from 2022 through 2023. Oil price volatility influences both borrowing costs and inflation expectations, which together determine the discount rates applied to long-duration assets like private equity holdings and development-stage real estate.
The simplified chain looks like this:
Oil ↑ → inflation ↑ → rates ↑ → cap rates and discount rates ↑ → asset values ↓, all else equal
Higher energy costs also drive wage inflation (workers demand raises to maintain purchasing power), construction cost escalation (oil-derived materials, freight, equipment fuel), and logistics expenses for portfolio companies. Inflation erodes purchasing power over time, and the compounding effect across an entire portfolio can be substantial.
The relationship is non-linear. Modest oil increases - say 20–30% above baseline - tend to be absorbed with mild inflation and minimal repricing. But once Brent moves above historical peaks like $100–$120 per barrel, inflation expectations shift, policy becomes more aggressive, and market behavior changes materially. CBRE's modeling of 20% and 40% oil price shocks demonstrates substantially greater cap rate sensitivity once those thresholds are crossed.
Near-Term Real Estate Impacts: Underwriting, Cash Flow, and Expenses
Higher oil prices increase property-level operating expenses in ways that show up quickly on operating statements. Utilities spike first, followed by vendor pricing for maintenance and services, insurance adjustments, and eventually property tax reassessments.
The data from recent cycles is stark. Across U.S. multifamily properties, operating expenses rose approximately 9.3% year-over-year by mid-2023, with utilities climbing roughly 7.8% and insurance surging 18.8%. Underwriters for multifamily, industrial, and office assets must adjust rent growth assumptions, expense growth rates, and reserve budgets during energy-driven inflationary periods - and many pro formas from 2020 or 2021 vintage deals did not anticipate this environment.
Net operating income margins compress when utilities and professional services escalate faster than rent. Private real estate investments often hedge against inflation over time because real estate values have historically increased with inflation, but the lag between cost increases and rent adjustments can create painful quarters or even years. Properties with adjustable rents can adjust to inflation, partially offsetting higher costs - but only if lease terms actually permit it.
High cap rates due to oil spikes lead to downward pressure on real estate valuations. Transaction volume slows in higher-rate environments, which affects appraisals, exit assumptions, and the ability to recycle capital through real estate investment groups and fund structures.
Key underwriting levers passive LPs should revisit:
- Expense growth rate assumptions, especially for energy and utilities - stress-test at oil above $100/barrel
- Lease structure: gross vs. NNN vs. hybrids; presence of expense stops and pass-through clauses
- Vendor contracts: whether costs are fixed or indexed to inflation
- Reserve and capital expenditure planning for energy efficiency retrofits
- Gap between projected rent escalations and projected cost escalations
Operating Expense Sensitivity and Lease Structures in Real Estate
Not all real estate investing carries the same exposure to energy costs. The property types most sensitive to oil-driven expense increases include:
- Older multifamily with landlord-paid heat and inefficient HVAC systems
- Hospitality properties with high energy usage for laundry, kitchens, and guest comfort
- Data centers dependent on massive cooling and power loads
- Cold storage and refrigerated warehouse facilities
- Large common-area retail and office buildings with shared energy systems
Higher energy prices can increase property-level expenses during inflation, but lease structures determine who bears the pain. Triple-net leases pass operating expenses - including utility, maintenance, and insurance costs - through to tenants, substantially reducing landlord exposure. Gross leases leave the landlord absorbing all increases. Expense stops create a middle ground where tenants pay up to a base amount and landlords absorb costs above it.
The highest risk sits in assets with limited cost pass-through: all-inclusive student housing, Class C workforce housing in energy-sensitive regions, certain assisted living facilities, and rural rental properties where transportation and fuel costs compound the problem.
Due-diligence questions for 506 Investor Group members evaluating deals:
- What is the historical utility expense volatility over past oil cycles?
- Has the sponsor budgeted energy-efficiency capital expenditures (LED, HVAC upgrades, solar)?
- What proportion of leases are NNN or include explicit utility pass-throughs?
- Do pro formas stress utility costs at oil levels of $100+ per barrel?
- What is the building envelope quality - insulation R-values, window ratings, roof condition?
- Are vendor contracts indexed to inflation or locked at fixed rates?
Development and Value-Add Real Estate Risk in a High-Oil Environment
Construction costs rise with higher oil prices due to material costs that many investors underestimate. Asphalt, roofing materials, PVC pipe, insulation, composite wood products, and plastics are all petroleum-derived. When oil surges, their prices follow. Oil price volatility affects construction material costs, and freight expenses for delivery amplify the impact. During 2021–2023, many ground-up and renovation projects incurred 10–20% cost overruns driven substantially by energy input inflation.
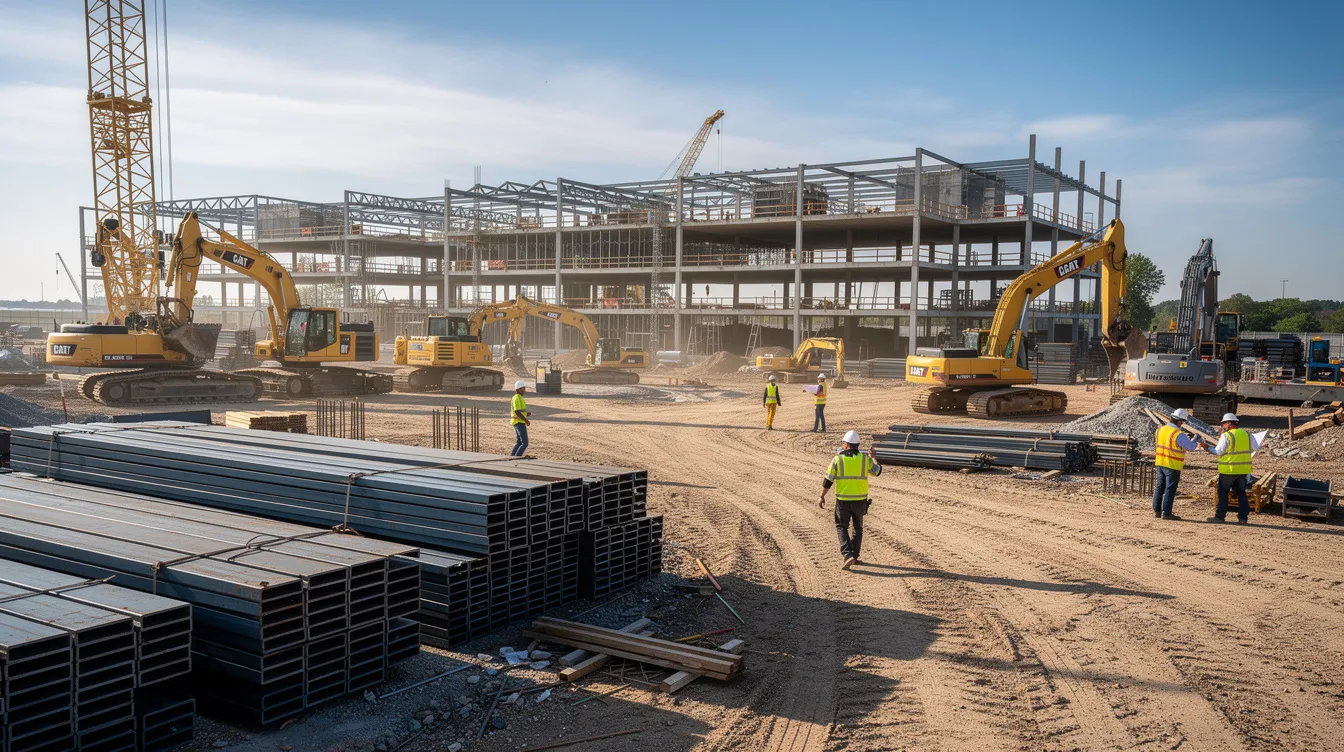
Ground-up development carries the heaviest exposure: longer build timelines mean more months of carrying costs while material prices, labor mobilization expenses, and interest on construction loans compound. Value-add renovations face less base-material risk if the scope is modest, but major system replacements (HVAC, roofing, plumbing) remain vulnerable.
Contractual protections matter more in volatile energy environments. Guaranteed maximum price contracts transfer overrun risk to contractors, though contractors may inflate bids to buffer their own exposure. Strong contractor balance sheets, indexation clauses for materials and fuel, and larger contingency budgets (8–15% of build cost rather than the typical 5%) become critical.
LP-oriented red flags in development deals:
- Budgets assuming material costs at pre-2020 or early 2021 levels
- Underestimated transportation and freight line items in pro formas
- Fixed-price supply contracts that lack inflation or fuel cost escalators
- Sponsors or contractors with weak balance sheets and limited history through inflation cycles
- Low contingency budgets relative to current market conditions
Rising oil prices may justify higher return hurdles on development and value-add deals to compensate for the incremental risk.
Long-Term Real Estate Positioning: Location, Energy Efficiency, and Asset Quality
Sustained periods of elevated energy costs reshape tenant preferences and pricing for decades, not just one cycle. Individual investors and institutional investors alike should think about which tangible assets will hold value through multiple energy regimes.
Energy-efficient buildings attract more stable investment demand and offer more stable operating profiles. Buildings with high-SEER HVAC, LED lighting, superior insulation, rooftop solar, and smart building systems demonstrate lower operating expense volatility, better tenant retention, and compressed cap rates - key characteristics of what the market increasingly defines as "core" quality.
Location dynamics shift meaningfully when gasoline and diesel stay expensive:
- Residential properties near transit hubs see steadier demand as commuting costs rise
- Rising oil prices shift operational demand towards logistics and industrial real estate near urban centers, where tenants reduce fuel spend on last-mile delivery
- Walkable, mixed-use urban infill outperforms exurban, car-dependent locations over time
- Geographic regions with cheap, stable energy (hydroelectric, nuclear, favorable renewable mix) gain competitive advantages
Secular winners and losers inside your real estate exposure:
- Winners: Core multifamily in transit-rich areas, infill industrial and last-mile logistics, energy-efficient office, modern warehouses and data centers with green power
- Losers: Older Class B/C suburban office, exurban multifamily with high utility burden, remote hospitality, cold storage in areas without on-site power generation
Private Equity: Sector Winners, Losers, and Deal Dynamics When Oil Rises
Higher oil prices create a sharply bifurcated landscape for private equity investments. Energy and energy-services buyout funds enjoy direct tailwinds - higher oil prices can boost cash flows and exit opportunities for energy-focused private equity. Midstream infrastructure, oilfield services, and companies offering efficiency or carbon management solutions see expanding margins and stronger deal activity.
On the other side, non-energy private equity sectors face margin compression from high oil prices. Consumer discretionary, transportation, airlines, trucking, packaging, and chemicals - any portfolio company with heavy logistics or petroleum-derived inputs - faces earnings pressure. GPs respond via pricing power strategies, cost pass-throughs, operational improvements, and sometimes hedging, but the margin squeeze is real.
The Lincoln Private Market Index for Q2 2026 showed private enterprise values growing approximately 1.9%, driven by energy companies benefiting from elevated oil and industrial infrastructure tied to data center spending. Revenue growth ran at 6.9% year-over-year versus CPI of 3.5%, suggesting that many private companies are managing to grow through inflation - but not all equally.
Higher borrowing costs due to oil-driven inflation reduce returns for private equity firms, particularly those that relied on cheap leverage and expected multiple expansion during lower-rate eras. Private equity investments typically have a 5-10 year holding period, meaning today's entry conditions will determine returns well into the 2030s. Valuation multiples compress when discount rates rise, and exit assumptions need to reflect a potentially sustained higher-rate environment.
What passive LPs should review when evaluating PE fund performance:
- Sector exposure: how much is committed to energy-sensitive vs. energy-benefiting sectors
- Hedging strategy and contractual pricing power within portfolio companies
- Leverage levels, debt cost, and interest rate reset risk
- Vintage performance history across prior oil cycles
- Manager operational discipline in inflationary, rate-rising environments
Venture Capital and Growth Equity in an Energy-Driven Inflation Cycle
Rising oil prices and the ensuing rate hikes from 2022 onward fundamentally changed the funding environment for venture capital and growth equity. Lower valuations, slower deal pace, and tougher down-round dynamics became the norm as discount rates climbed and the open market for IPOs contracted.
Several sub-sectors stand to benefit from persistently high energy costs:
- Climate tech and energy storage companies addressing grid reliability
- Grid optimization and demand management software
- EV charging infrastructure and sustainable logistics
- Efficiency platforms that help companies manage energy costs - these have built-in tailwinds when energy is expensive
The contrast is stark for capital-intensive, high-burn startups whose models assumed cheap capital and low operating costs. Server farm expenses, transportation logistics, and wage inflation all eat into burn rates, while fundraising slows and valuations compress.
Guidance for accredited investors allocating to VC funds:
- Prioritize managers with proven discipline through the 2008–2009 and 2020–2022 downturns
- Seek realistic exit timelines rather than reliance on multiple expansion as the primary return driver
- Favor exposure to energy transition themes and companies with inflation-resilient revenue models
- Spread allocations across essential services, software efficiency, and natural resources rather than purely speculative growth
Hedge Funds, Commodities, and Direct Energy Exposure as Inflation Hedges
Certain hedge fund strategies can directly monetize oil volatility and inflation trends, potentially offsetting pressure on illiquid alternative investments elsewhere in your portfolio. Global macro funds, commodity trading advisors, and long short equity strategies focused on energy have historically performed well during supply shocks.
Commodity investments and energy futures can serve as portfolio-level hedges, though they carry basis risk, roll yield complications (contango vs. backwardation), and timing risk. For many passive investors, access to energy-linked strategies comes through specialized alternative assets - not just public ETFs. Hedge fund managers running these strategies may offer investors meaningful diversification benefits, but the fee structures tend to include performance fees and higher fees than traditional investments.
Due-diligence priorities for these strategies:
- Historical performance during prior oil supply disruptions and geopolitical events
- Liquidity terms, gates, and redemption policies - understand the illiquid nature before committing
- Correlation of returns to inflation and oil price movements
- Downside behavior during disinflationary or demand-collapse scenarios
- How these funds complement your existing real estate and private equity exposure
Private Debt, Direct Lending, and Floating-Rate Opportunities
Higher oil prices and inflation push policy rates higher, which raises yields on floating-rate private debt and direct lending instruments. For accredited investors seeking income under inflationary market conditions, senior secured floating-rate debt can offer investors attractive risk-adjusted returns.
But credit risk cuts both ways. Energy-sensitive borrowers - transportation companies, lower-margin manufacturers, consumer businesses with thin pricing power - may face earnings stress, raising default risk in certain private debt funds. The distinction between senior secured, asset-backed lending and mezzanine or unitranche structures matters significantly: senior positions have collateral and better recovery rates; subordinated debt bears more downside protection risk.
Practical evaluation points for 506 Investor Group members:
- Interest-rate benchmarks in debt agreements: SOFR-based floating vs. fixed
- Covenant quality: interest coverage ratios, oil input cost sensitivity triggers
- Sector concentration of borrowers - avoid overexposure to energy-sensitive industries
- Manager track record managing credit cycles and economic downturns
Portfolio Construction: Balancing Alternative Investments Across Oil Cycles
Pension funds and large institutional investors have long used alternative investments to reduce reliance on traditional markets and manage inflation risk. As of 2019, 75% of Yale's endowment was in alternative investments, and Yale's endowment allocated 10% to real estate from 1998 to 2018 - a deliberate strategy to capture the diversification benefits and inflation hedging that real assets and private companies provide.
Alternative investments may reach $24.5 trillion by 2028, reflecting growing recognition that many alternatives offer investors low correlation to stocks and bonds. But many alternative investments are illiquid compared to traditional assets, which makes portfolio construction during volatile oil cycles more consequential - you can't easily rebalance. Oversight also varies widely, and many private offerings are not registered with the Securities and Exchange Commission.
Private alternative investments can reduce overall portfolio risk during inflation when structured thoughtfully. Alternative investments can provide diversification benefits for portfolios, but only if you diversify across asset classes, sectors, and geographies rather than concentrating in a single strategy.
Key characteristics of a resilient alternative investment mix under volatile oil prices:
- Blend of real assets (real estate, infrastructure assets like toll roads, commodities) with growth alternatives (private equity, venture capital) and income strategies (private debt, core real estate with long term leases)
- Varied duration profiles and mixed fixed vs. floating-rate exposure
- Geographic diversification - Western Europe is generally more sensitive to energy shocks than the U.S. due to import dependency
- Stress-testing under multiple scenarios: oil at $60, oil at $120, and oil shock plus recession - evaluating cash flow, distributions, capital calls, and overall portfolio risk
Private real estate investments often hedge against inflation over longer holding periods. Real estate values historically increase with inflation, making real estate a cornerstone of inflation-aware portfolio construction for high net worth individuals.
Using the 506 Investor Group Advantage in a High-Oil, High-Inflation Environment
The 506 Investor Group serves sophisticated accredited investors who collaborate on alternative investments without sponsors or capital raisers influencing the conversation. No self-promotion, zero conflicts of interest - just unbiased investment opportunities sourced exclusively from members.
In a high-oil, high-inflation environment where macro headwinds compress investment returns, the group's collective buying power becomes even more valuable. With over 4,000 members and more than $1.5 billion invested through deals with special negotiated terms, lower fees and better structures directly improve net returns at a time when gross returns face pressure.
Member-sourced deal flow and shared due diligence help identify real estate investments, private equity funds, private debt opportunities, and hedge funds positioned for rising or volatile oil prices. When retail investors are left guessing, 506 Investor Group members can leverage unbiased peer insights to evaluate risk scenarios, stress tests, and cash flow assumptions in any deal tied to energy costs - turning volatility from a threat into a filter for better capital deployment.
Key Takeaways and Action Checklist for Accredited Passive Investors
How rising oil prices typically affect alternative investments:
- Real estate: higher operating expenses, cap rate expansion on lower-quality assets, but inflation-linked rent growth and energy-efficient properties can hold value
- Private equity: energy-focused funds benefit; non-energy sectors face margin compression and higher borrowing costs
- Venture capital: valuations compress under higher rates, but energy transition and efficiency themes gain tailwinds
- Hedge funds and commodities: can directly hedge oil volatility and provide downside protection for the broader portfolio
- Private debt: floating-rate yields rise, but credit risk increases for energy-sensitive borrowers
Action checklist before committing to a new alternative investment:
- Review energy and transportation cost exposure in the deal's operating budget
- Confirm expense pass-through mechanisms in lease structures or portfolio company contracts
- Evaluate leverage levels and rate sensitivity - fixed vs. floating, current vs. reset rates
- Assess the manager's track record through prior inflation and oil cycles
- Stress-test pro formas under oil at $100+ per barrel and rising rate scenarios
- Verify contingency budgets for development deals reflect current material and freight costs
Oil price volatility is not purely a risk - it also creates differentiated opportunities in energy-linked strategies, inflation-resilient real estate, agricultural products and commodity investments, and private debt with favorable securities and structures. The key is scrutinizing terms, understanding who bears the cost, and investing alongside people who share your commitment to rigorous due diligence.
Economic growth cycles will continue to intersect with energy markets in unpredictable ways. Disciplined underwriting, collaboration with other 506 Investor Group members, and continuous reassessment of portfolio positioning as energy markets and interest rates evolve will separate investors who merely survive oil volatility from those who use it to build durable wealth.
The Impact of Rising Oil Prices on Alternative Investments: Private Equity, Real Estate, and Beyond
Oil prices rarely stay quiet for long - and when they move, the ripple effects reach far beyond the gas pump. For accredited passive investors holding positions in private equity, real estate, private debt, and other alternative assets, understanding how energy costs reshape valuations, cash flow, and deal terms is essential to protecting and growing wealth.
Executive Snapshot: Why Oil Prices Matter for Accredited Alternative Investors
Fluctuations in oil prices serve as a macroeconomic driver influencing alternative asset performance across nearly every sector. When Brent crude collapsed from $115 to below $30 between 2014 and 2016, energy-focused funds suffered while consumer-oriented strategies benefited from lower input costs. The reversal came hard: after Russia's invasion of Ukraine in early 2022, oil surged past $120 per barrel, triggering cost-push inflation that forced aggressive central bank tightening. Rising oil prices trigger cost-push inflation and tighter monetary policy, and the downstream consequences hit alternative investments in ways that stocks and bonds often don't prepare you for.
The directional impacts break down roughly like this:
- Higher oil → higher inflation and interest rates → valuation pressure on growth-oriented private equity and venture capital; compressed multiples and higher discount rates
- Mixed effects on income-oriented real estate → rent escalation may lag rising expenses; NNN lease structures fare better than gross leases
- Potential upside for energy-focused funds → midstream infrastructure, energy services, and commodity strategies can benefit directly
- Private debt and floating-rate instruments → yields rise with rates, but credit risk increases for energy-sensitive borrowers
Alternative investments often have higher return potential than traditional investments, but that potential comes with exposure to macro forces like oil that public mutual funds and stock investments rarely force you to confront directly.
For members of the 506 Investor Group - accredited passive investors sharing deal flow and due diligence without sponsor influence - the practical concerns are specific: Will your portfolio cash flow hold up if utilities and construction costs jump? Are the deals you're evaluating underwritten for today's energy environment or for 2020-era assumptions? And are you positioned to capitalize on the opportunities that volatile oil markets create?
This article focuses on practical implications and actionable guidance rather than macro theory, drawing on 2022–2026 data where available.
How Oil Prices Feed Through to Inflation, Rates, and Alternative Assets
The transmission mechanism from oil to your alternative investment portfolio is straightforward, even if the timing isn't always predictable.
Oil functions as a foundational input cost. When crude rises, production costs climb across manufacturing, logistics, agriculture, and construction. Those increases flow into the Producer Price Index (PPI) and eventually consumer prices (CPI). Sustained energy-driven inflation can raise interest rates as central banks respond - exactly what happened during the Fed's aggressive hiking cycle from 2022 through 2023. Oil price volatility influences both borrowing costs and inflation expectations, which together determine the discount rates applied to long-duration assets like private equity holdings and development-stage real estate.
The simplified chain looks like this:
Oil ↑ → inflation ↑ → rates ↑ → cap rates and discount rates ↑ → asset values ↓, all else equal
Higher energy costs also drive wage inflation (workers demand raises to maintain purchasing power), construction cost escalation (oil-derived materials, freight, equipment fuel), and logistics expenses for portfolio companies. Inflation erodes purchasing power over time, and the compounding effect across an entire portfolio can be substantial.
The relationship is non-linear. Modest oil increases - say 20–30% above baseline - tend to be absorbed with mild inflation and minimal repricing. But once Brent moves above historical peaks like $100–$120 per barrel, inflation expectations shift, policy becomes more aggressive, and market behavior changes materially. CBRE's modeling of 20% and 40% oil price shocks demonstrates substantially greater cap rate sensitivity once those thresholds are crossed.
Near-Term Real Estate Impacts: Underwriting, Cash Flow, and Expenses
Higher oil prices increase property-level operating expenses in ways that show up quickly on operating statements. Utilities spike first, followed by vendor pricing for maintenance and services, insurance adjustments, and eventually property tax reassessments.
The data from recent cycles is stark. Across U.S. multifamily properties, operating expenses rose approximately 9.3% year-over-year by mid-2023, with utilities climbing roughly 7.8% and insurance surging 18.8%. Underwriters for multifamily, industrial, and office assets must adjust rent growth assumptions, expense growth rates, and reserve budgets during energy-driven inflationary periods - and many pro formas from 2020 or 2021 vintage deals did not anticipate this environment.
Net operating income margins compress when utilities and professional services escalate faster than rent. Private real estate investments often hedge against inflation over time because real estate values have historically increased with inflation, but the lag between cost increases and rent adjustments can create painful quarters or even years. Properties with adjustable rents can adjust to inflation, partially offsetting higher costs - but only if lease terms actually permit it.
High cap rates due to oil spikes lead to downward pressure on real estate valuations. Transaction volume slows in higher-rate environments, which affects appraisals, exit assumptions, and the ability to recycle capital through real estate investment groups and fund structures.
Key underwriting levers passive LPs should revisit:
- Expense growth rate assumptions, especially for energy and utilities - stress-test at oil above $100/barrel
- Lease structure: gross vs. NNN vs. hybrids; presence of expense stops and pass-through clauses
- Vendor contracts: whether costs are fixed or indexed to inflation
- Reserve and capital expenditure planning for energy efficiency retrofits
- Gap between projected rent escalations and projected cost escalations
Operating Expense Sensitivity and Lease Structures in Real Estate
Not all real estate investing carries the same exposure to energy costs. The property types most sensitive to oil-driven expense increases include:
- Older multifamily with landlord-paid heat and inefficient HVAC systems
- Hospitality properties with high energy usage for laundry, kitchens, and guest comfort
- Data centers dependent on massive cooling and power loads
- Cold storage and refrigerated warehouse facilities
- Large common-area retail and office buildings with shared energy systems
Higher energy prices can increase property-level expenses during inflation, but lease structures determine who bears the pain. Triple-net leases pass operating expenses - including utility, maintenance, and insurance costs - through to tenants, substantially reducing landlord exposure. Gross leases leave the landlord absorbing all increases. Expense stops create a middle ground where tenants pay up to a base amount and landlords absorb costs above it.
The highest risk sits in assets with limited cost pass-through: all-inclusive student housing, Class C workforce housing in energy-sensitive regions, certain assisted living facilities, and rural rental properties where transportation and fuel costs compound the problem.
Due-diligence questions for 506 Investor Group members evaluating deals:
- What is the historical utility expense volatility over past oil cycles?
- Has the sponsor budgeted energy-efficiency capital expenditures (LED, HVAC upgrades, solar)?
- What proportion of leases are NNN or include explicit utility pass-throughs?
- Do pro formas stress utility costs at oil levels of $100+ per barrel?
- What is the building envelope quality - insulation R-values, window ratings, roof condition?
- Are vendor contracts indexed to inflation or locked at fixed rates?
Development and Value-Add Real Estate Risk in a High-Oil Environment
Construction costs rise with higher oil prices due to material costs that many investors underestimate. Asphalt, roofing materials, PVC pipe, insulation, composite wood products, and plastics are all petroleum-derived. When oil surges, their prices follow. Oil price volatility affects construction material costs, and freight expenses for delivery amplify the impact. During 2021–2023, many ground-up and renovation projects incurred 10–20% cost overruns driven substantially by energy input inflation.
Ground-up development carries the heaviest exposure: longer build timelines mean more months of carrying costs while material prices, labor mobilization expenses, and interest on construction loans compound. Value-add renovations face less base-material risk if the scope is modest, but major system replacements (HVAC, roofing, plumbing) remain vulnerable.
Contractual protections matter more in volatile energy environments. Guaranteed maximum price contracts transfer overrun risk to contractors, though contractors may inflate bids to buffer their own exposure. Strong contractor balance sheets, indexation clauses for materials and fuel, and larger contingency budgets (8–15% of build cost rather than the typical 5%) become critical.
LP-oriented red flags in development deals:
- Budgets assuming material costs at pre-2020 or early 2021 levels
- Underestimated transportation and freight line items in pro formas
- Fixed-price supply contracts that lack inflation or fuel cost escalators
- Sponsors or contractors with weak balance sheets and limited history through inflation cycles
- Low contingency budgets relative to current market conditions
Rising oil prices may justify higher return hurdles on development and value-add deals to compensate for the incremental risk.
Long-Term Real Estate Positioning: Location, Energy Efficiency, and Asset Quality
Sustained periods of elevated energy costs reshape tenant preferences and pricing for decades, not just one cycle. Individual investors and institutional investors alike should think about which tangible assets will hold value through multiple energy regimes.
Energy-efficient buildings attract more stable investment demand and offer more stable operating profiles. Buildings with high-SEER HVAC, LED lighting, superior insulation, rooftop solar, and smart building systems demonstrate lower operating expense volatility, better tenant retention, and compressed cap rates - key characteristics of what the market increasingly defines as "core" quality.
Location dynamics shift meaningfully when gasoline and diesel stay expensive:
- Residential properties near transit hubs see steadier demand as commuting costs rise
- Rising oil prices shift operational demand towards logistics and industrial real estate near urban centers, where tenants reduce fuel spend on last-mile delivery
- Walkable, mixed-use urban infill outperforms exurban, car-dependent locations over time
- Geographic regions with cheap, stable energy (hydroelectric, nuclear, favorable renewable mix) gain competitive advantages
Secular winners and losers inside your real estate exposure:
- Winners: Core multifamily in transit-rich areas, infill industrial and last-mile logistics, energy-efficient office, modern warehouses and data centers with green power
- Losers: Older Class B/C suburban office, exurban multifamily with high utility burden, remote hospitality, cold storage in areas without on-site power generation
Private Equity: Sector Winners, Losers, and Deal Dynamics When Oil Rises
Higher oil prices create a sharply bifurcated landscape for private equity investments. Energy and energy-services buyout funds enjoy direct tailwinds - higher oil prices can boost cash flows and exit opportunities for energy-focused private equity. Midstream infrastructure, oilfield services, and companies offering efficiency or carbon management solutions see expanding margins and stronger deal activity.
On the other side, non-energy private equity sectors face margin compression from high oil prices. Consumer discretionary, transportation, airlines, trucking, packaging, and chemicals - any portfolio company with heavy logistics or petroleum-derived inputs - faces earnings pressure. GPs respond via pricing power strategies, cost pass-throughs, operational improvements, and sometimes hedging, but the margin squeeze is real.
The Lincoln Private Market Index for Q2 2026 showed private enterprise values growing approximately 1.9%, driven by energy companies benefiting from elevated oil and industrial infrastructure tied to data center spending. Revenue growth ran at 6.9% year-over-year versus CPI of 3.5%, suggesting that many private companies are managing to grow through inflation - but not all equally.
Higher borrowing costs due to oil-driven inflation reduce returns for private equity firms, particularly those that relied on cheap leverage and expected multiple expansion during lower-rate eras. Private equity investments typically have a 5-10 year holding period, meaning today's entry conditions will determine returns well into the 2030s. Valuation multiples compress when discount rates rise, and exit assumptions need to reflect a potentially sustained higher-rate environment.
What passive LPs should review when evaluating PE fund performance:
- Sector exposure: how much is committed to energy-sensitive vs. energy-benefiting sectors
- Hedging strategy and contractual pricing power within portfolio companies
- Leverage levels, debt cost, and interest rate reset risk
- Vintage performance history across prior oil cycles
- Manager operational discipline in inflationary, rate-rising environments
Venture Capital and Growth Equity in an Energy-Driven Inflation Cycle
Rising oil prices and the ensuing rate hikes from 2022 onward fundamentally changed the funding environment for venture capital and growth equity. Lower valuations, slower deal pace, and tougher down-round dynamics became the norm as discount rates climbed and the open market for IPOs contracted.
Several sub-sectors stand to benefit from persistently high energy costs:
- Climate tech and energy storage companies addressing grid reliability
- Grid optimization and demand management software
- EV charging infrastructure and sustainable logistics
- Efficiency platforms that help companies manage energy costs - these have built-in tailwinds when energy is expensive
The contrast is stark for capital-intensive, high-burn startups whose models assumed cheap capital and low operating costs. Server farm expenses, transportation logistics, and wage inflation all eat into burn rates, while fundraising slows and valuations compress.
Guidance for accredited investors allocating to VC funds:
- Prioritize managers with proven discipline through the 2008–2009 and 2020–2022 downturns
- Seek realistic exit timelines rather than reliance on multiple expansion as the primary return driver
- Favor exposure to energy transition themes and companies with inflation-resilient revenue models
- Spread allocations across essential services, software efficiency, and natural resources rather than purely speculative growth
Hedge Funds, Commodities, and Direct Energy Exposure as Inflation Hedges
Certain hedge fund strategies can directly monetize oil volatility and inflation trends, potentially offsetting pressure on illiquid alternative investments elsewhere in your portfolio. Global macro funds, commodity trading advisors, and long short equity strategies focused on energy have historically performed well during supply shocks.
Commodity investments and energy futures can serve as portfolio-level hedges, though they carry basis risk, roll yield complications (contango vs. backwardation), and timing risk. For many passive investors, access to energy-linked strategies comes through specialized alternative assets - not just public ETFs. Hedge fund managers running these strategies may offer investors meaningful diversification benefits, but the fee structures tend to include performance fees and higher fees than traditional investments.
Due-diligence priorities for these strategies:
- Historical performance during prior oil supply disruptions and geopolitical events
- Liquidity terms, gates, and redemption policies - understand the illiquid nature before committing
- Correlation of returns to inflation and oil price movements
- Downside behavior during disinflationary or demand-collapse scenarios
- How these funds complement your existing real estate and private equity exposure
Private Debt, Direct Lending, and Floating-Rate Opportunities
Higher oil prices and inflation push policy rates higher, which raises yields on floating-rate private debt and direct lending instruments. For accredited investors seeking income under inflationary market conditions, senior secured floating-rate debt can offer investors attractive risk-adjusted returns.
But credit risk cuts both ways. Energy-sensitive borrowers - transportation companies, lower-margin manufacturers, consumer businesses with thin pricing power - may face earnings stress, raising default risk in certain private debt funds. The distinction between senior secured, asset-backed lending and mezzanine or unitranche structures matters significantly: senior positions have collateral and better recovery rates; subordinated debt bears more downside protection risk.
Practical evaluation points for 506 Investor Group members:
- Interest-rate benchmarks in debt agreements: SOFR-based floating vs. fixed
- Covenant quality: interest coverage ratios, oil input cost sensitivity triggers
- Sector concentration of borrowers - avoid overexposure to energy-sensitive industries
- Manager track record managing credit cycles and economic downturns
Portfolio Construction: Balancing Alternative Investments Across Oil Cycles
Pension funds and large institutional investors have long used alternative investments to reduce reliance on traditional markets and manage inflation risk. As of 2019, 75% of Yale's endowment was in alternative investments, and Yale's endowment allocated 10% to real estate from 1998 to 2018 - a deliberate strategy to capture the diversification benefits and inflation hedging that real assets and private companies provide.
Alternative investments may reach $24.5 trillion by 2028, reflecting growing recognition that many alternatives offer investors low correlation to stocks and bonds. But many alternative investments are illiquid compared to traditional assets, which makes portfolio construction during volatile oil cycles more consequential - you can't easily rebalance.
Private alternative investments can reduce overall portfolio risk during inflation when structured thoughtfully. Alternative investments can provide diversification benefits for portfolios, but only if you diversify across asset classes, sectors, and geographies rather than concentrating in a single strategy.
Key characteristics of a resilient alternative investment mix under volatile oil prices:
- Blend of real assets (real estate, infrastructure assets like toll roads, commodities) with growth alternatives (private equity, venture capital) and income strategies (private debt, core real estate with long term leases)
- Varied duration profiles and mixed fixed vs. floating-rate exposure
- Geographic diversification - Western Europe is generally more sensitive to energy shocks than the U.S. due to import dependency
- Stress-testing under multiple scenarios: oil at $60, oil at $120, and oil shock plus recession - evaluating cash flow, distributions, capital calls, and overall portfolio risk
Private real estate investments often hedge against inflation over longer holding periods. Real estate values historically increase with inflation, making real estate a cornerstone of inflation-aware portfolio construction for high net worth individuals.
Using the 506 Investor Group Advantage in a High-Oil, High-Inflation Environment
The 506 Investor Group serves sophisticated accredited investors who collaborate on alternative investments without sponsors or capital raisers influencing the conversation. No self-promotion, zero conflicts of interest - just unbiased investment opportunities sourced exclusively from members.
In a high-oil, high-inflation environment where macro headwinds compress investment returns, the group's collective buying power becomes even more valuable. With over 4,000 members and more than $1.5 billion invested through deals with special negotiated terms, lower fees and better structures directly improve net returns at a time when gross returns face pressure.
Member-sourced deal flow and shared due diligence help identify real estate investments, private equity funds, private debt opportunities, and hedge funds positioned for rising or volatile oil prices. When retail investors are left guessing, 506 Investor Group members can leverage unbiased peer insights to evaluate risk scenarios, stress tests, and cash flow assumptions in any deal tied to energy costs - turning volatility from a threat into a filter for better capital deployment.
Key Takeaways and Action Checklist for Accredited Passive Investors
How rising oil prices typically affect alternative investments:
- Real estate: higher operating expenses, cap rate expansion on lower-quality assets, but inflation-linked rent growth and energy-efficient properties can hold value
- Private equity: energy-focused funds benefit; non-energy sectors face margin compression and higher borrowing costs
- Venture capital: valuations compress under higher rates, but energy transition and efficiency themes gain tailwinds
- Hedge funds and commodities: can directly hedge oil volatility and provide downside protection for the broader portfolio
- Private debt: floating-rate yields rise, but credit risk increases for energy-sensitive borrowers
Action checklist before committing to a new alternative investment:
- Review energy and transportation cost exposure in the deal's operating budget
- Confirm expense pass-through mechanisms in lease structures or portfolio company contracts
- Evaluate leverage levels and rate sensitivity - fixed vs. floating, current vs. reset rates
- Assess the manager's track record through prior inflation and oil cycles
- Stress-test pro formas under oil at $100+ per barrel and rising rate scenarios
- Verify contingency budgets for development deals reflect current material and freight costs
Oil price volatility is not purely a risk - it also creates differentiated opportunities in energy-linked strategies, inflation-resilient real estate, agricultural products and commodity investments, and private debt with favorable securities and structures. The key is scrutinizing terms, understanding who bears the cost, and investing alongside people who share your commitment to rigorous due diligence.